Arrows International Realty
  • Home
  • Study
    • Rights of Property >
      • Real Right and Credit
      • Rights to the land and Rights to the building
    • the Building Lots and Buildings Transaction Business Act >
      • Laws Related to Real Estate Transaction in Japan
      • (1) Laws Concerning Land Use
      • (2) Laws Concerning Construction of Buildings
      • (3) Laws Regulating Real Estate Companies
      • (4) Laws and Regulations Concerning Advertisement
      • (5) Laws Concerning Contracts Including Sales Contracts and Lease Contracts
      • (6) Laws concerning Titles and Rights
      • (7) Laws Concerning Real Property Registration
      • (8) Laws Concerning Condominium Management
      • (9) Laws Concerning Defects (Faults, etc.) of Housing Properties
    • How to and Procedures >
      • Process of Real Estate Sale
      • Process of Real Estate Purchase >
        • the Process of Buying a House
        • Housing Prices
        • the Living Environment
        • the Budget
        • Find a Home
        • Choosing a Real Estate Agency
        • Financial Planning and Mortgage
        • Making the Final Decision to Purchase
        • Concluding a Sales Contract
        • Delivery of the Property
      • Cost by Transaction
      • Important Points Explanation
      • Real Estate Sales Contract
      • Property Condition Confirmation
      • Facilities and Equipment List
    • Building Management >
      • Process of Residential Property Management
      • Process of Real Estate Leasing >
        • Idea of Lease Agreement
      • Process of Second House Management
    • Related Acts
    • Glossary >
      • Real Estate Glossary in Japan
    • Tax in Japan >
      • Consumption Tax
      • Property Tax
      • Capital Gain Tax
      • Withholding Tax
      • Taxes on Gifts and Inheritances
    • Q&A >
      • Q&A
  • Local
    • Learning
  • Latest Information
    • Latest News
    • We Love Kyoto
  • Column
  • About Us
    • Records
    • Partners
    • Cookie Notice
    • Sitemap
  • Contact

8/26/2022

Housing Taxes: Real Estate Acquisition Tax 2

Read Now
 

Real Estate Acquisition Tax 

Special Exception for Reduction on Residential Land
If the house meets the same floor area and other requirements as described in the Special Provisions for Tax Base on Acquisition of Certain Residential Property and the acquisition of land meets one of the requirements in the table below, the larger amount of either 1. or 2. can be deducted from the tax for the residential land.
  1. 45,000 yen
  2. Assessed value per square meter of site*1 x 2 times the floor area of the house (up to a maximum of 200 square meters) x 3%*2
*1 For residential land, the amount after applying the special exception to the tax base until March 31, 2024.
*2 Tax rate until March 31, 2024 under the special exception for reduced tax rates for land and housing acquisitions
In principle, the collection of real estate acquisition tax is deferred if a new residential house is built within three years of the acquisition of the land.
Picture
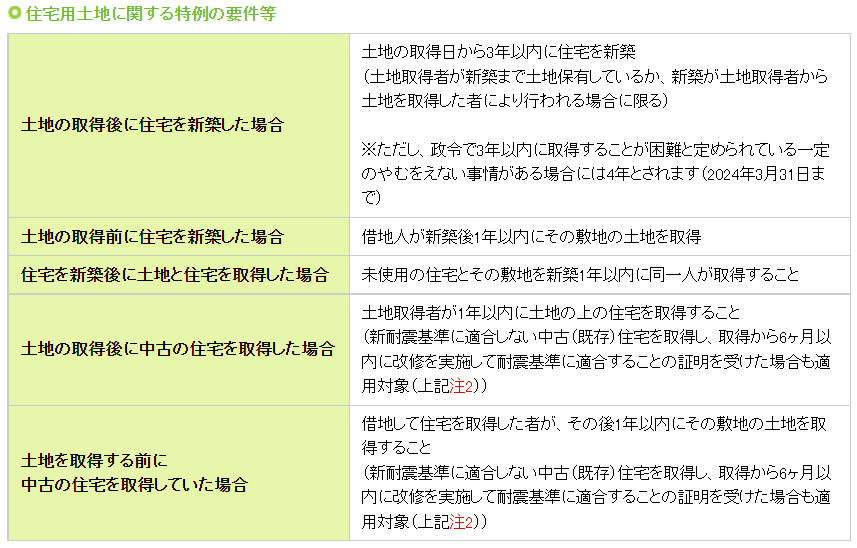
≪Requirements for special exemptions for residential land≫
  • When a new house is built after the acquisition of land:
A new house is built within 3 years of the date of acquisition of the land. 
(Provided that the land acquirer holds the land until a new house is built or the new house is built by the person who acquires the land from the land acquirer.)
* However, if certain unforeseeable circumstances arise that make it difficult to acquire the property within three years as stipulated by the government ordinance, the period will be extended to four years (until March 31, 2024).
  • When a new house is built before the land is acquired:
The leaseholder acquires the land on which the house is located within one year of construction.
  • When land and a house are acquired after the house is newly built:
A house that hasn't been used since being built and its grounds must be acquired by the same person within one year of construction.
  • When an existing house is acquired after the acquisition of land:
The land acquirer acquires a house on the land within one year.
​(This also applies to cases where an existing house that does not conform to the new earthquake-proof standard is acquired and renovated within 6 months of acquisition to conform to the earthquake-proof standard (see Note 2 above)).
  • When you had acquired an existing home before the acquisition of the land:
A person who acquired a house on leased land acquires the land on which the house is located within one year thereafter.
​(This also applies to cases where an existing house that does not conform to the new earthquake-proof standard is acquired and renovated within 6 months of acquisition to conform to the earthquake-proof standard (see Note 2 above)).
Picture
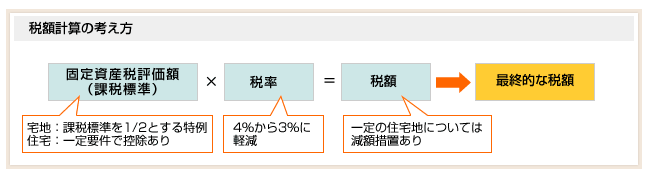
How to Calculate Tax
Assessed value of fixed assets (tax base) x Tax rate = Tax amount  ➡ Final tax amount
Notes:
​Assessed value of fixed assets 
Residential land: Special exception to halve the taxable base
Housing: Deduction available under certain conditions
Tax rate
Reduced from 4% to 3%.
Tax amount
Reduction measures are available for certain residential land.

Share

8/23/2022

Housing Taxes: Real Estate Acquisition Tax 1

Read Now
 

Real Estate Acquisition Tax

Real estate acquisition tax is a tax paid when real estate is acquired. In principle, the tax amount is calculated by multiplying the assessed value of fixed property by a tax rate of 4%. In the case of a newly constructed building that has not yet been assessed for property tax, the value of the building is calculated based on the standards for calculating the value of fixed property by the prefectural governor. The principle method of determining the tax amount is as follows.

Picture
  • Tax amount = assessed taxable value of fixed property (tax base) x tax rate
Special Tax Rate Reduction for Land and Housing Acquisitions
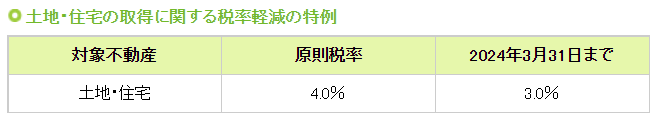
The tax rate applicable to the acquisition of land and housing is subject to a special tax rate of 3% until March 31, 2024.
Picture
≪Reduced tax rate on land≫
Eligible property  ・・・ Land and housing
Basic tax rate  ・・・ 4.0%
​Until March 31, 2024 ・・・ 3.0%
Special Taxation Standards for Residential Land and Land Whose Assessed Value Is Determined on the Basis of Residential Land
If residential land is acquired by March 31, 2024, the tax base for residential land will be reduced by one-half.
Picture
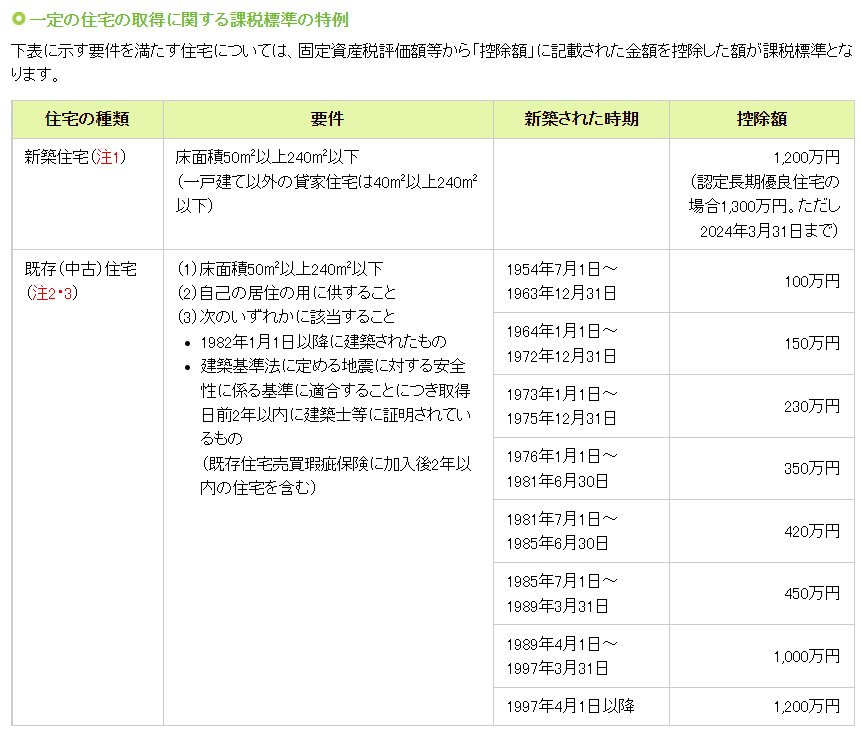
≪Special provisions for tax base on acquisition of certain houses≫
For houses that meet the requirements shown in the table below, the amount shown in the "Deduction Amount" section will be deducted from the assessed taxable value:  tax base = assessed taxable value - deduction amount
Types of houses 
1. New housing (Note 1)
Requirement(s): Floor area of 50 ㎡ or more but less than 240 ㎡.
(40 ㎡ to 240 ㎡ or more for rental housing other than single-family houses)
Amount deducted: 12 million yen
(13 million yen for certified excellent long-term housing, but only until March 31, 2024)

2. Existing (used) housing (Note 2 & 3)
Requirement(s):
(1) Floor area of 50 ㎡ to 240 ㎡ or more
(2) To be used for one's own residence
(3) One of the following is applicable
  • Built on or after January 1, 1982
  • Certified by an architect within two years prior to the date of acquisition as conforming to the earthquake safety standards stipulated in the Building Standards Law (Including homes sold within 2 years of purchasing Existing Home Sales Defects Insurance)
Date built: July 1, 1954 to December 31, 1963 ⇒ Amount deducted: 1 million yen
Date built: January 1, 1964 to December 31, 1972 ⇒ Amount deducted: 1.5 million yen
Date built: January 1, 1973 to December 31, 1975 ⇒ Amount deducted: 2.3million yen
Date built: January 1, 1976 to June 30, 1981 ⇒ Amount deducted: 3.5million yen
Date built: July 1, 1981 to June 30, 1985 ⇒ Amount deducted: 4.2 million yen
Date built: July 1, 1985 to March 31, 1989 ⇒ Amount deducted: 4.5 million yen
Date built: April 1, 1989 to March 31, 1997 ⇒ Amount deducted: 10 million yen
Date built: On and after April 1, 1997    ⇒ Amount deducted: 12 million yen
(Note 1) Taxation on residential high-rise buildings (tower condominiums, etc. exceeding 60 meters in height)
  1. In the case of acquiring the exclusive use portion (for residential use) of a building such as a tower condominium with a height exceeding 60 meters in which residential units are located on more than one floor, the real estate acquisition tax - which is imposed by deeming the acquisition of a house with a value equivalent to the amount obtained by proportionally dividing the assessed value of the building by the floor area ratio of the exclusive area - is corrected by the "exclusive floor area correction rate by floor area" to reflect the trend of changes in the transaction unit price per floor area due to differences in the floor area of the exclusive area by the floor level where the units are located.
  2. Eligible tower condominiums are new residential high-rise buildings taxable on and after April 2018.
  3. The correction rate for exclusive floor area by floor level is 100 + 10/39 x (N-1) for the number of N floors.
(Note 2) Special exception for reduction for acquisition of existing Houses nonconforming to seismic standards
  1. If you acquire an existing (used) house that does not conform to the earthquake resistance standards, make improvements to it within 6 months of acquisition, and move into it after receiving certification that it conforms to the earthquake resistance standards, under the "Special Exception for Tax Base on Certain Housing Acquisitions" for existing (used) housing, the deductible amount determined by the date built will be reduced from the tax due by multiplying by the tax rate.
  2. If you acquire an existing house that does not conform to the earthquake resistance standards and also its site, the "Special Exception for Reduction in Value of Land for Residential Use" will also apply to the site.
(Note 3) There are measures designed to reduce the real estate acquisition tax imposed on the buyer-reseller when the buyer-reseller purchases an existing (used) house, makes improvements to certain housing quality, and then resells the house.

Share

8/19/2022

Housing Taxes: Registration and License Tax

Read Now
 

Registration and License Tax

Registration and license tax is a tax imposed when registering land, buildings, etc. For ownership registration, the tax amount is calculated by multiplying the assessed taxable value of the property by the designated tax rate. The amount of tax for mortgage registrations is calculated by multiplying the amount of the claim (the amount of the mortgage or other loans) by the designated tax rate. ​Tax payment is to be made when applying for registration. If the building is newly constructed and does not yet have a property tax assessment, the assessed value is calculated based on the New Building Value Approval Standard Table by the Legal Affairs Bureau.
Picture
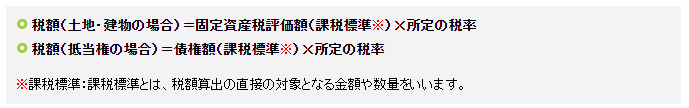
  • Tax amount (for land and buildings) = assessed taxable value of fixed property (tax base*) x designated tax rate
  • Tax amount (for mortgages) = amount of claim (tax base*) x designated tax rate
​*The tax base is the amount or quantity directly subject to tax calculation.
Special Tax Rate Reductions for Housing
In the case of the registration of a house with a floor area of 50㎡ or more, the reduced registration and license tax rate will be applied if the house is certified by the mayor of the municipality where the house is located as meeting the requirements in the table below.
Further special measures are available for Certified Long-term Quality Housing*1 and Certified Low Carbon Housing*2.
*1 Long-term quality housing certified under the provisions of the Act on Promoting the Development of Long-Term Quality Housing, hereinafter referred to as "Certified Long-Term Quality Housing.
*2 Low-carbon housing certified in accordance with the provisions of the Act Concerning the Promotion of Low Carbon Emission in Urban Areas, hereinafter referred to as "Certified Low Carbon Housing". It includes housing that is a specified building to be developed through a certified intensive urban development project that is deemed to be a certified low-carbon housing.
Picture
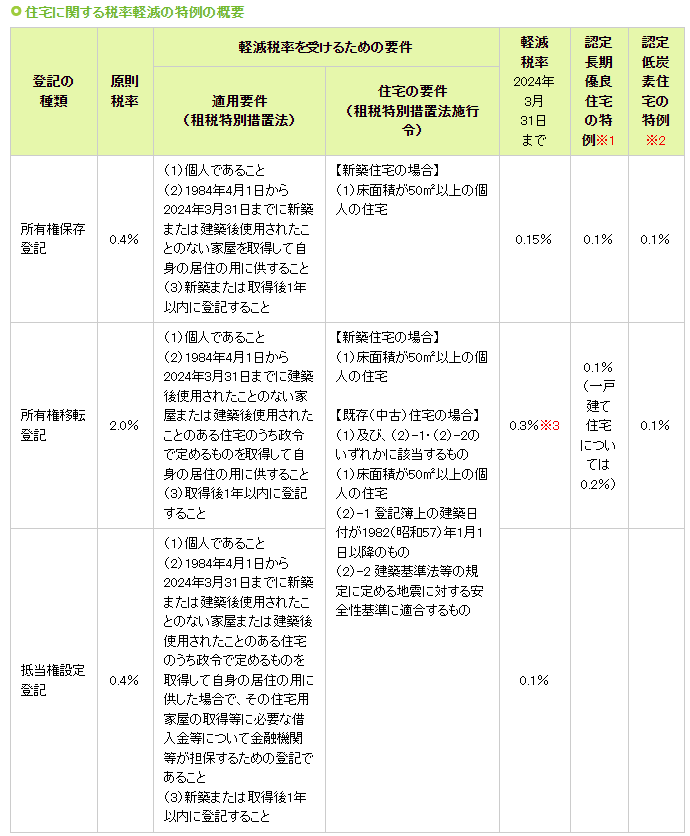
≪Overview of the special tax rate reductions for housing≫
Types of registration (1-3)
1. Registration of preservation of ownership ・・・ 0.4% (Basic tax rate)
  • Requirements to qualify for the reduced tax rate
Eligibility Requirements (Special Taxation Measures Law)
(1) Be private individuals.
(2) Acquire between April 1, 1984 and March 31, 2024 a newly built house or a house that has not been used since its construction and use it for one's own residence.
(3) Register it within a year of construction or acquisition.​
Housing Requirements (Special Taxation Measures Law Enforcement Order)
In the case of a newly built house:
(1) Private housing with a floor area of 50㎡ or more
  • Reduced tax rate until March 31, 2024 ・・・ 0.15% 
  • Special Exception for Certified Long-Term Quality Housing*1 ・・・ 0.1% 
  • Special Exception for Certified Low Carbon Housing*2 ・・・ 0.1% 

2. Registration of transfer of ownership ・・・ 2.0% (Basic tax rate)
  • Requirements to qualify for the reduced tax rate
Eligibility Requirements (Special Taxation Measures Law)
(1) Be private individuals.
(2) Acquire between April 1, 1984 and March 31, 2024 a house that has not been used since its construction or a house that has been used since its construction -which is specified by a Cabinet Order - and has been used for one's own residence.
(3) Register it within a year of acquisition.
Housing Requirements (Special Taxation Measures Law Enforcement Order)
In the case of a newly built house:
(1) Private housing with a floor area of 50㎡ or more
In the case of  an existing (used) house:
When either (1), (2)-1, or (2)-2 below applies, the tax rate will be reduced.
(1) Individual residences with a floor area of 50 ㎡or more
(2)-1 Those whose construction date on the registry is January 1, 1982 or later.
(2)-2 Those that comply with the earthquake safety standards stipulated in the Building Standard Law and other regulations.
  • Reduced tax rate until March 31, 2024 ・・・ 0.3% *3
  • Special Exception for Certified Long-Term Quality Housing ・・・ 0.1%  (a detached house: 0.2%)
  • Special Exception for Certified Low Carbon Housing ・・・ 0.1% 

3. Registration of mortgage ・・・ 0.4% (Basic tax rate)
  • Requirements to qualify for the reduced tax rate
Eligibility Requirements (Special Taxation Measures Law)
(1) Be private individuals.
(2) Acquire between April 1, 1984 and March 31, 2024 a newly built house, a house that has never been used since its construction, or a house that has been used since its construction - which is specified by a Cabinet Order - and has been used for one's own residence as specified by a Cabinet Order, and the registration is for the purpose of securing loans necessary for the acquisition of the residential house from a financial institution.
(3) Register it within a year of construction or acquisition.
Housing Requirements (Special Taxation Measures Law Enforcement Order)
In the case of a newly built house:
(1) Private housing with a floor area of 50㎡ or more
  • Reduced tax rate until March 31, 2024 ・・・ 0.15% 
  • Special Exception for Certified Long-Term Quality Housing*1 ・・・ 0.1% 
  • Special Exception for Certified Low Carbon Housing*2 ・・・ 0.1% 
In the case of  an existing (used) house:
When either (1), (2)-1, or (2)-2 below applies, the tax rate will be reduced.
(1) Individual residences with a floor area of 50 ㎡or more
(2)-1 Those whose construction date on the registry is January 1, 1982 or later.
(2)-2 Those that comply with the earthquake safety standards stipulated in the Building Standard Law and other regulations.
  • Reduced tax rate until March 31, 2024 ・・・ 0.1%

*1*2 The special provisions for Certified Long-term Quality Housing and Certified Low Carbon Housing are applicable when a private individual builds a new Certified Long-term Quality Housing or Certified Low Carbon Housing within a certain period or acquires one that has never been used after construction, uses it for the individual's residence, and registers the preservation of ownership or the transfer of ownership within a year of acquisition.
*3 If a private individual acquires an existing residential building for which certain additions, alterations, etc. have been made by a real estate agent between April 1, 2014 and March 31, 2024, the tax rate for the registration of ownership transfer of the residential building will be reduced to 0.1% when the registration is made within a year of acquisition.
Special Tax Rate Reduction for Land
The registration and license tax for the transfer of ownership of land is reduced by a time-limited measure.
Picture
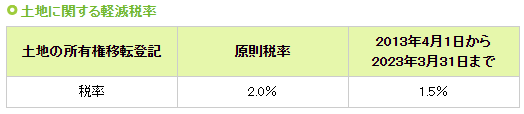
≪Reduced tax rates on land≫
Registration of transfer of ownership of land
Basic tax rate ・・・ 2.0% 
​From April 1, 2013 to March 31, 2023 ・・・ 1.5% 

Share

8/5/2022

Housing Taxes: Consumption Tax

Read Now
 

Housing Taxes: Consumption Tax

When purchasing a house from a real estate company or building a house, as a general rule, consumption tax is imposed on the price as the taxable base. Land is exempt from taxation, but buildings are taxable. In principle, buildings sold after October 1, 2019, will be subject to a 10% consumption tax on the transfer price. A brokerage fee to a real estate company is also subject to consumption tax with the amount of the fee as the taxable base. However, this excludes cases where the seller is an individual who is not a consumption taxable business operator or a tax-exempt business operator.

Picture
Tax amount = the price of the building x the tax rate of 10% (national tax 7.8% + local tax 2.2%)
The Settlement of Taxes and Public Dues
It is common practice for the seller and the buyer to settle the property tax and city planning tax associated with the sale and purchase of the house. It should be noted that the settlement of taxes and public dues for the building is included in the consumption taxable amount.

The owner of the property as of January 1 shall be liable for the property tax and city planning tax. Even if the house is transferred to another party after January 1, the taxpayer will remain the same. Therefore, in the sale and purchase of real estate, including housing, it is customary to prorate the property tax and city planning tax on a daily basis based on the date of delivery and settle the taxes between the seller and the buyer.

However,  this is a "voluntary" settlement between the seller and the buyer in the purchase and sale of a house, and the tax and public dues settlement to be given and received is treated as part of the transfer price of the building. This amount is not considered taxes for tax purposes. Therefore, when consumption tax is imposed on the building, the consumption tax is calculated by including the settlement of taxes and public dues paid by the buyer to the seller in the transfer consideration.

Share

8/2/2022

Housing Taxes: Stamp Tax

Read Now
 

​Taxes When Buying a Home

When buying a house, you will have to pay stamp tax, consumption tax, registration and license tax, real estate acquisition tax, and other taxes.

Stamp Tax

Stamp tax is a tax that is imposed on contracts when a purchase agreement for the sale of a house or a mortgage contract is signed. The  amount of tax is determined by the amount of money stated in the contract. In principle, the tax is paid by affixing revenue stamps to the contract and stamping a seal.
Picture
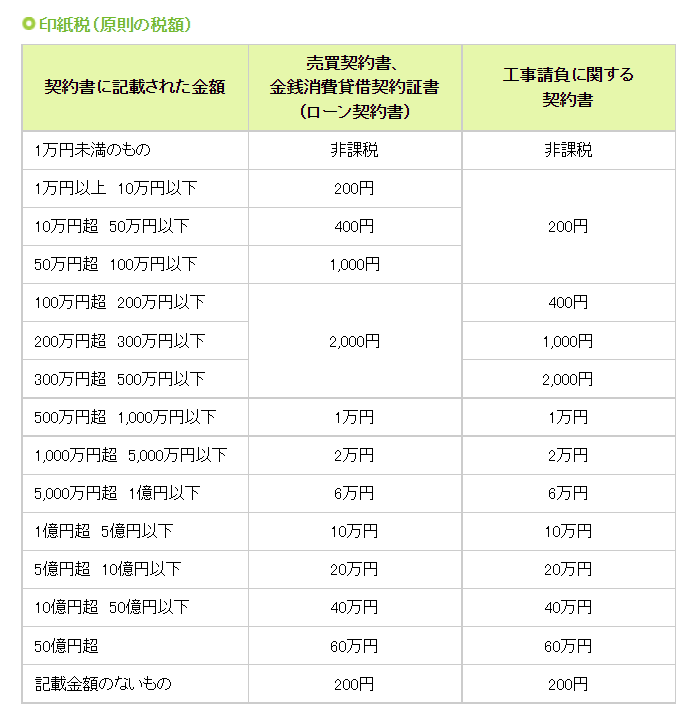
 ≪Stamp Tax ( general tax amount)≫
 Sales Contracts and Loan Agreements 
  • The amount written in the contract < 10,000 yen ----- tax exempt
  • 10 ,000 yen < The amount written in the contract <= 100,000 yen ----- 200 yen
  • 100,000 yen < The amount written in the contract <= 500,000 yen ----- 400 yen
  • 500,000 yen < The amount written in the contract <= 1,000,000 yen ----- 1,000 yen
  • 1,000,000 yen < The amount written in the contract <= 5,000,000 yen ----- 2,000 yen
  • 5,000,000 yen < The amount written in the contract <= 10,000,000 yen ----- 10,000 yen
  • 10,000,000 yen < The amount written in the contract <= 50,000,000 yen ----- 20,000 yen
  • 50,000,000 yen < The amount written in the contract <= 100,000,000 yen ----- 60,000 yen
  • 100,000,000 yen < The amount written in the contract <= 500,000,000 yen ----- 100,000 yen
  •  500,000,000 yen < The amount written in the contract <= 1,000,000,000 yen ----- 200,000 yen
  • 1,000,000,000 yen  < The amount written in the contract <= 5,000,000,000 yen -----400,000 yen
  • 5,000,000,000 yen < The amount written in the contract ----- 600,000 yen
  • The amount not stated in the contract ----- 200 yen
Construction Contracts
  • The amount written in the contract < 10,000 yen ----- tax exempt
  • 10 ,000 yen < The amount written in the contract <= 1,000,000 yen ----- 200 yen
  • 1,000,000 yen < The amount written in the contract <= 2,000,000 yen ----- 400 yen
  • 2,000,000 yen < The amount written in the contract <= 3,000,000 yen ----- 1,000 yen
  • 3,000,000 yen < The amount written in the contract <= 5,000,000 yen ----- 2,000 yen
  • 5,000,000 yen < The amount written in the contract <= 10,000,000 yen ----- 10,000 yen
  • 10,000,000 yen < The amount written in the contract <= 50,000,000 yen ----- 20,000 yen
  • 50,000,000 yen < The amount written in the contract <= 100,000,000 yen ----- 60,000 yen
  • 100,000,000 yen < The amount written in the contract <= 500,000,000 yen ----- 100,000 ye
  • ​ 500,000,000 yen < The amount written in the contract <= 1,000,000,000 yen ----- 200,000 yen
  • 1,000,000,000 yen  < The amount written in the contract <= 5,000,000,000 yen ----- 400,000 yen
  • 5,000,000,000 yen < The amount written in the contract ----- 600,000 yen
  • The amount not stated in the contract ----- 200 yen
Tax Reduction for Home Acquisition
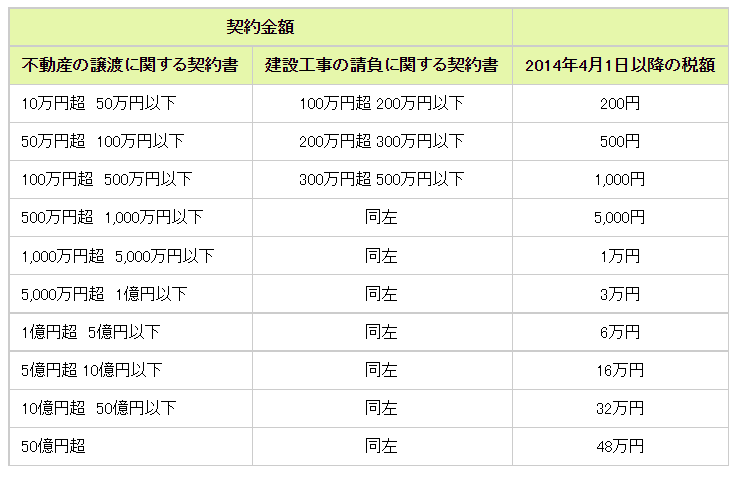
Stamp tax on sales contracts for the purchase of real estate such as houses and contracts for the construction of houses is reduced as follows from April 1, 2014 to March 31, 2024.
Picture
Real Estate Transfer Agreement
  • 100,000 yen < The contract amount <= 500,000 yen -----200 yen
  • 500,000 yen < The contract amount <= 1,000,000 yen -----500 yen
  • 1,000,000 yen < The contract amount <= 5,000,000 yen ----- 1,000 yen
  • 5,000,000 yen < The contract amount <= 10,000,000 yen ----- 5,000 yen
  • 10,000,000 yen < The contract amount <= 50,000,000 yen ----- 10,000 yen
  • 50,000,000 yen < The contract amount <= 100,000,000 yen ----- 30,000 yen
  • 100,000,000 yen < The contract amount <= 500,000,000 yen ----- 60,000 yen
  •  500,000,000 yen < The contract amount <= 1,000,000,000 yen ----- 160,000 yen
  • 1,000,000,000 yen  < The contract amount <= 5,000,000,000 yen ----- 320,000 yen
  • 5,000,000,000 yen < The contract amount ----- 480,000 yen
​Construction Contract Agreement
  • 1,000,000 yen < The contract amount <= 2,000,000 yen -----200 yen
  • 2,000,000 yen < The contract amount <= 3,000,000 yen -----500 yen
  • 3,000,000 yen < The contract amount <= 5,000,000 yen ----- 1,000 yen
  • 5,000,000 yen < The contract amount <= 10,000,000 yen ----- 5,000 yen
  • 10,000,000 yen < The contract amount <= 50,000,000 yen ----- 10,000 yen
  • 50,000,000 yen < The contract amount <= 100,000,000 yen ----- 30,000 yen
  • 100,000,000 yen < The contract amount <= 500,000,000 yen ----- 60,000 yen
  •  500,000,000 yen < The contract amount <= 1,000,000,000 yen ----- 160,000 yen
  • 1,000,000,000 yen  < The contract amount <= 5,000,000,000 yen ----- 320,000 yen
  • 5,000,000,000 yen < The contract amount ----- 480,000 yen
*​Only sales contracts for the purchase of real estate and contracts for the construction of housing are eligible for the reduction.

Share

Details

    Author

    Arrows International Realty Corp.

    Archives

    October 2024
    June 2023
    April 2023
    March 2023
    February 2023
    January 2023
    December 2022
    November 2022
    October 2022
    September 2022
    August 2022
    July 2022
    June 2022
    May 2022
    April 2022
    March 2022
    February 2022
    January 2022
    December 2021
    November 2021
    October 2021
    July 2021
    January 2021
    December 2020
    September 2020
    August 2020
    July 2020
    June 2020
    May 2020

    Categories

    All
    360°
    Affidavit
    Airbnb
    Apartment
    Apartmment
    Application
    Architect
    Bank Account
    Bank Loan
    Bath Unit
    Brokerage Fee
    Buyandsell
    Cadastral Map
    Camping
    City Planning
    City Planning Areas
    Condo
    Construction Company
    Consulting
    Custom Home
    Demolition
    Depreciation
    Design
    Disaster Countermeasure
    Disaster Information
    Disaster Prevention
    Dismantlement
    Districts
    DIY
    Do It Yourself
    Documents
    Door Lock
    Double Window Sash
    Earthquake Resistance Standards
    Earthquake-Resistant
    Eel's Bed
    Escape Route
    Established A Corporation
    Evacuation Site
    Financing
    Fire Insurance
    Fixed Term Building Lease Agreement
    Flood
    For Rent
    For Sale
    Fusuma
    Garden
    General Corporation
    Go To Travel Campaign
    Guarantor Company
    Guesthouse
    Hatsu-bon
    Heavy Rain
    Home Loan
    Hotel
    House
    Housing Fire Alarm
    Housing Loan
    Inn
    Inns And Hotels Act
    Insulation
    Investment
    Investment Loan
    Investment Strategy
    Key Exchange
    Kitchen
    Kyo-machiya
    Kyoto
    Kyoto Shinkin Bank
    Land
    Land For Sale
    Land Use Zones
    Landslide Disaster
    Lease Agreement
    Lessee
    Lessor
    License
    Lot Number
    Machiya
    Machiya Design
    Machiya Loan
    Maintenance
    Management
    Mediation Contract
    Minpaku
    Money Flow
    Monthly Cost
    Mortgage
    Move
    National Strategic Special Zones Act
    Negotiation
    New Construction
    Non-rebuilding
    Obon
    Old House
    Omoteya Style
    Overlap Roofing
    PR Visa
    Price Reduce
    Private Lodging
    Private Lodging Business Act
    Property Management
    Purchase
    RC Structure
    RC-Structure
    Real Estate
    Real Estate Agents
    Real Estate Assessment
    Real Estate Investing
    Real Estate Ownership
    Real Estate Tour
    Rebuilding
    Registration Certificate
    Regular Rental Agreement
    Reinforcement
    REINS
    Remodeling
    Remote
    Remote Work
    Renovated
    Renovation
    Rent
    Repair
    Reserve Fund For Repair
    Residential Address
    Rethatching
    Risk Management
    Roof Painting
    Ryokan
    S Structure
    S-Structure
    Sales Contract
    Second Home
    Seismic Control
    Sell The Property
    Set-back
    Shiga
    Shin-bon
    Single-story Home
    Sliding Door
    Soundproofing
    SRC Structure
    SRC-Structure
    Stamp Duty
    Stamp Tax
    Standards
    Structure
    Swimming
    Tatami Mat
    Tax
    Tax Return
    Tea House
    The Building Standards Act
    Tile Roofing
    Transaction
    Tsubo
    Tsunami
    Ura-bon-e"
    Vacation Home
    Vacation Home Management
    W Structure
    W-Structure
    Waterproof
    WFH
    WFH In Kyoto
    Withholding Tax
    Zones

    RSS Feed

Home
About
Contact

​Jp
CN

Real Estate agent in Kyoto, Buy and Sell, Leasing, Renovation and Construction, Management for Investment and Vacation Property, Professional Services for International Customers. We deal in KyoMachiya houses, detached and attached Houses, new and old Condominium Apartments, Block of Apartments and Buildings for Commercial, Residential and Investments use, Manage and Support Operation and New Development of Guesthouse, Ryokan and Hotel, Total Supports for Land and Buildings Real Estate in Kyoto.
Yours sincerely, Founder Ken Hayashi
Real Estate Broker Company License No. Kyoto-Fu Governor ( 2 ) 14044 , ​Member of Kyoto Association of Residential Land Building Business
  • Home
  • Study
    • Rights of Property >
      • Real Right and Credit
      • Rights to the land and Rights to the building
    • the Building Lots and Buildings Transaction Business Act >
      • Laws Related to Real Estate Transaction in Japan
      • (1) Laws Concerning Land Use
      • (2) Laws Concerning Construction of Buildings
      • (3) Laws Regulating Real Estate Companies
      • (4) Laws and Regulations Concerning Advertisement
      • (5) Laws Concerning Contracts Including Sales Contracts and Lease Contracts
      • (6) Laws concerning Titles and Rights
      • (7) Laws Concerning Real Property Registration
      • (8) Laws Concerning Condominium Management
      • (9) Laws Concerning Defects (Faults, etc.) of Housing Properties
    • How to and Procedures >
      • Process of Real Estate Sale
      • Process of Real Estate Purchase >
        • the Process of Buying a House
        • Housing Prices
        • the Living Environment
        • the Budget
        • Find a Home
        • Choosing a Real Estate Agency
        • Financial Planning and Mortgage
        • Making the Final Decision to Purchase
        • Concluding a Sales Contract
        • Delivery of the Property
      • Cost by Transaction
      • Important Points Explanation
      • Real Estate Sales Contract
      • Property Condition Confirmation
      • Facilities and Equipment List
    • Building Management >
      • Process of Residential Property Management
      • Process of Real Estate Leasing >
        • Idea of Lease Agreement
      • Process of Second House Management
    • Related Acts
    • Glossary >
      • Real Estate Glossary in Japan
    • Tax in Japan >
      • Consumption Tax
      • Property Tax
      • Capital Gain Tax
      • Withholding Tax
      • Taxes on Gifts and Inheritances
    • Q&A >
      • Q&A
  • Local
    • Learning
  • Latest Information
    • Latest News
    • We Love Kyoto
  • Column
  • About Us
    • Records
    • Partners
    • Cookie Notice
    • Sitemap
  • Contact